JH-2614 · Off-plan
330 Riverside Crescent, Sobha Hartland II
MBR City · 1 bed · 496 sq ft

An off-plan lagoon one-bed resold below the developer’s price, where the exit rests on the frontage holding its premium.
- Asking price
- USD 327 KAED 1.20 M
- Modelled net yield
- 5.0%
- Data confidence
- Limited
- Best aligned with
- Capital appreciation
- Portfolio diversification
Why this is on our list
Below the original price
Resold by an original buyer at AED 1.2M, against an original price of AED 1.25M.
On the lagoon
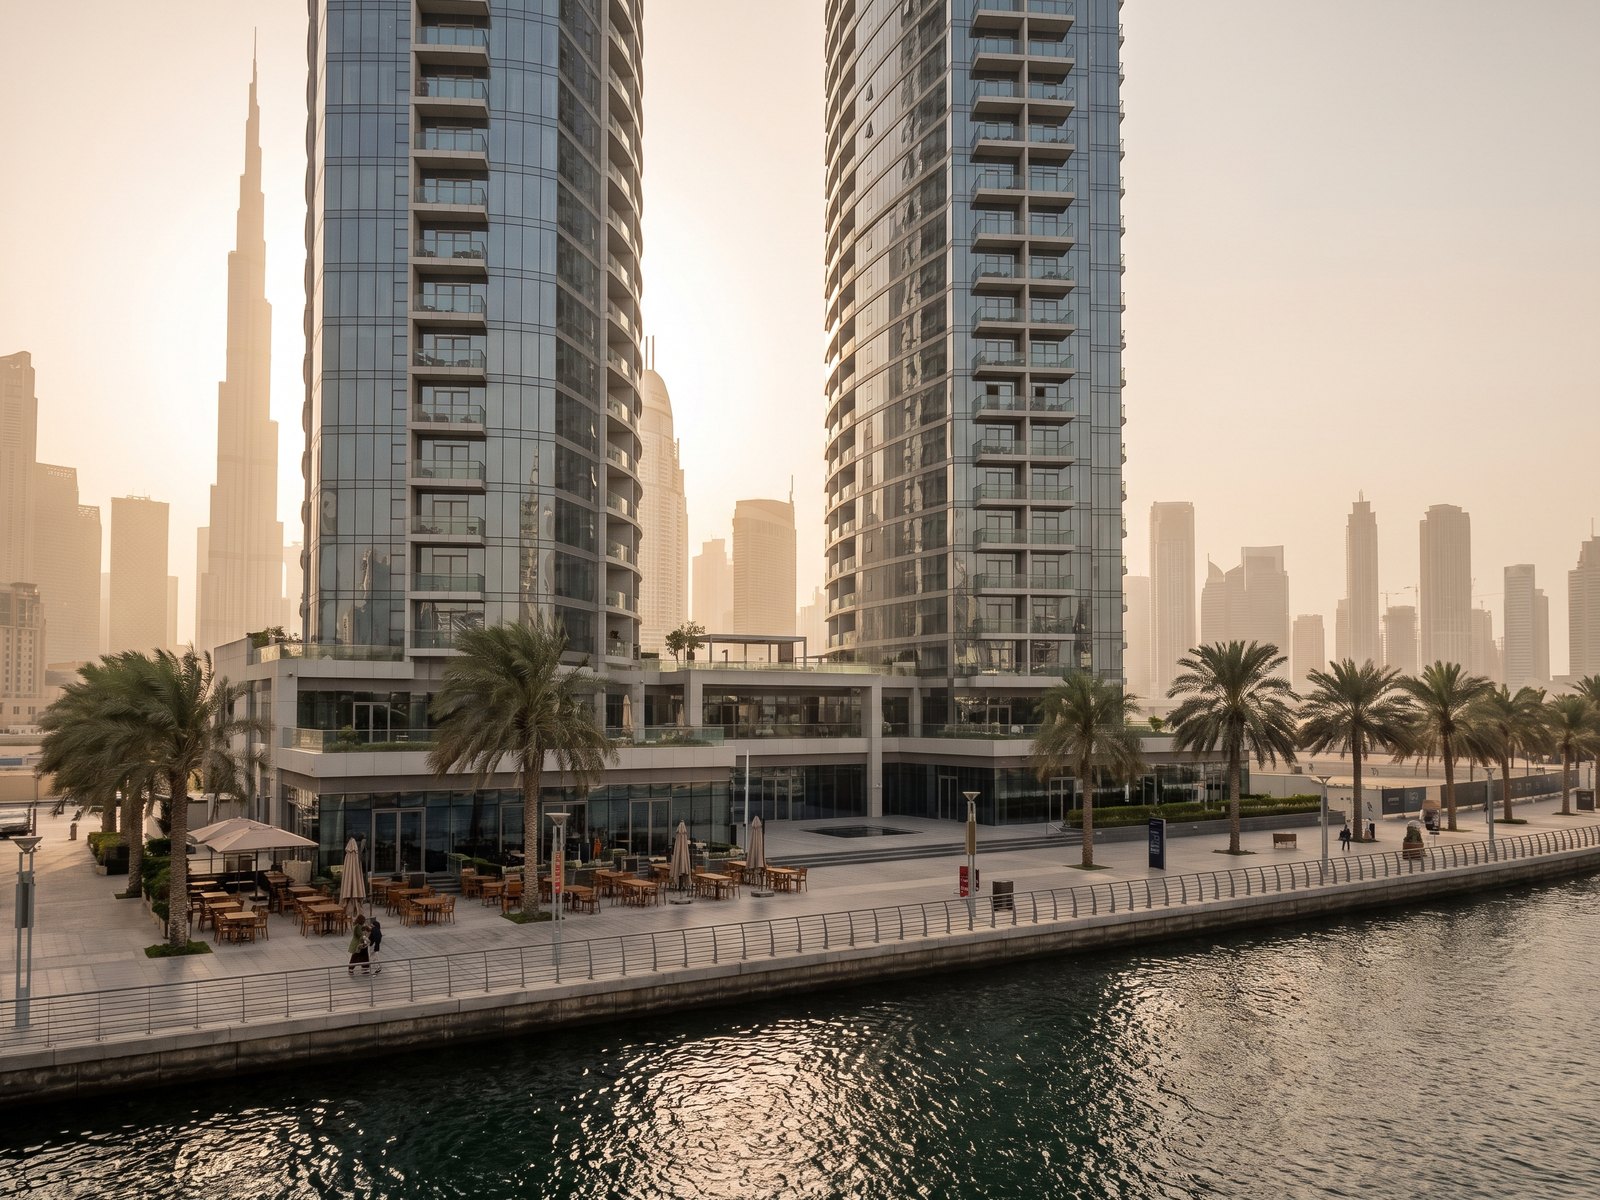
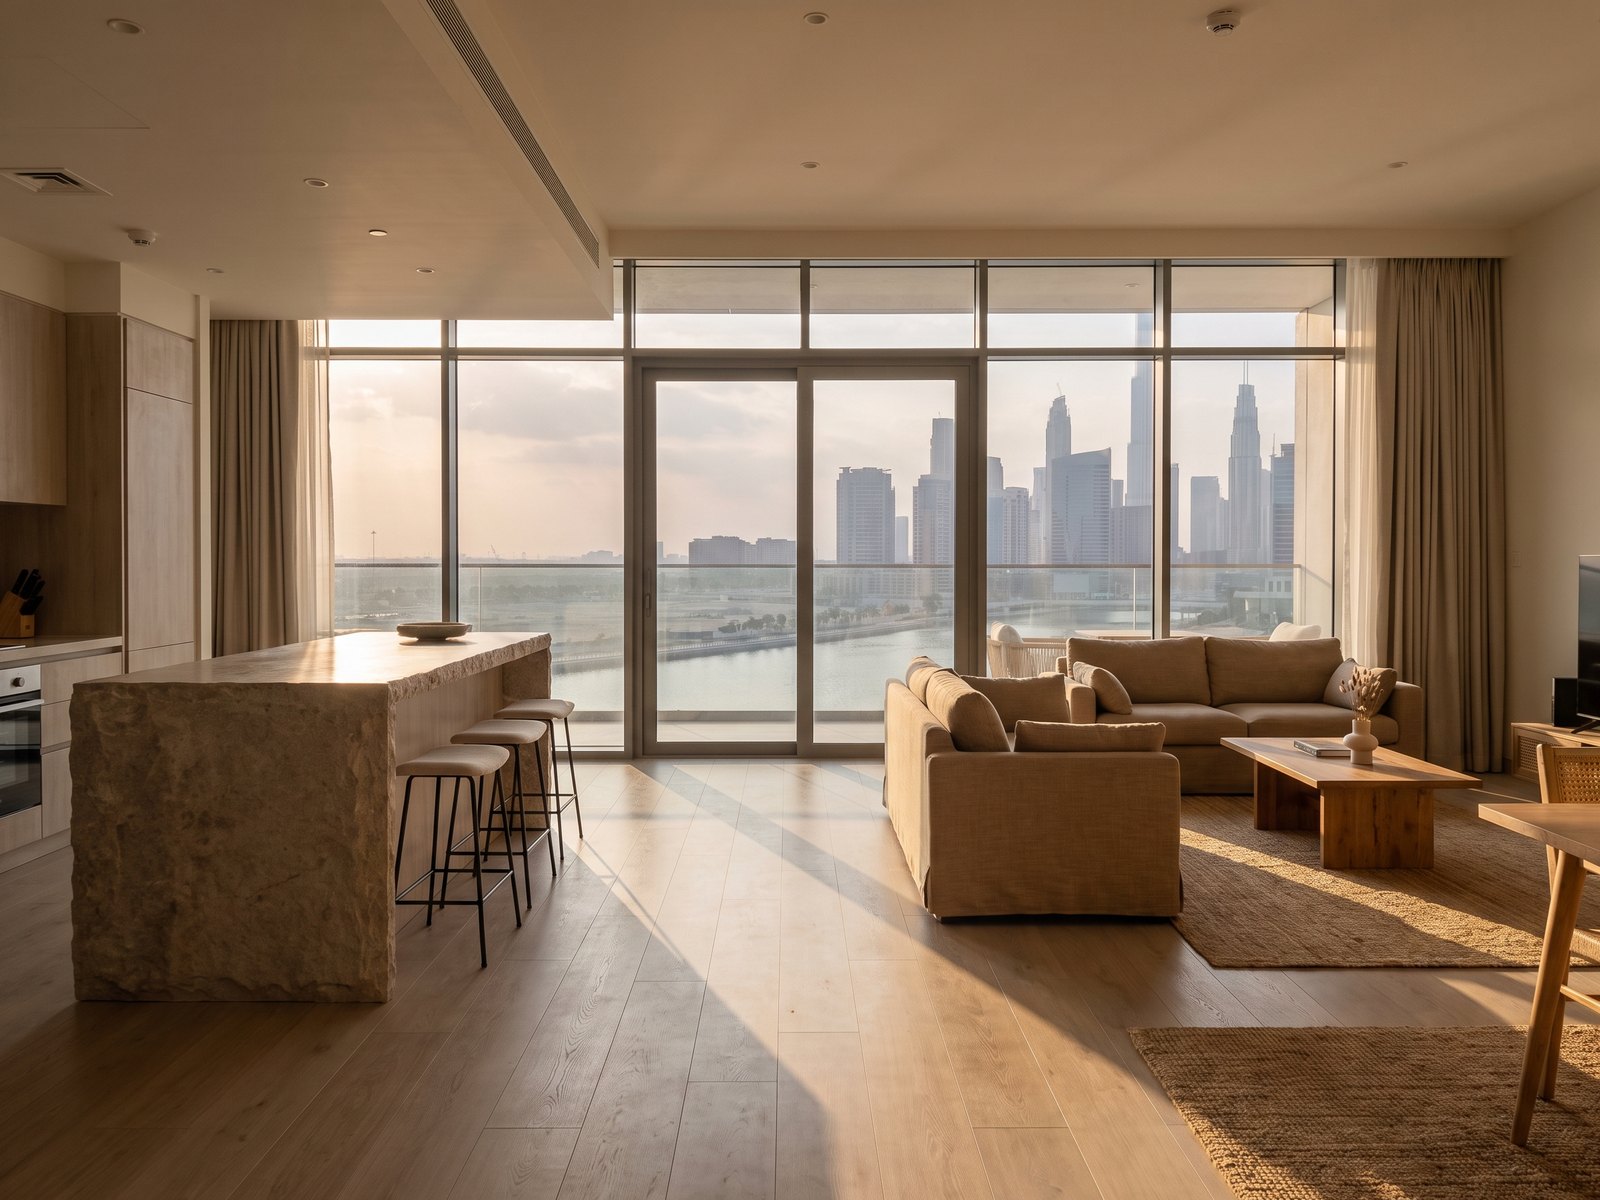
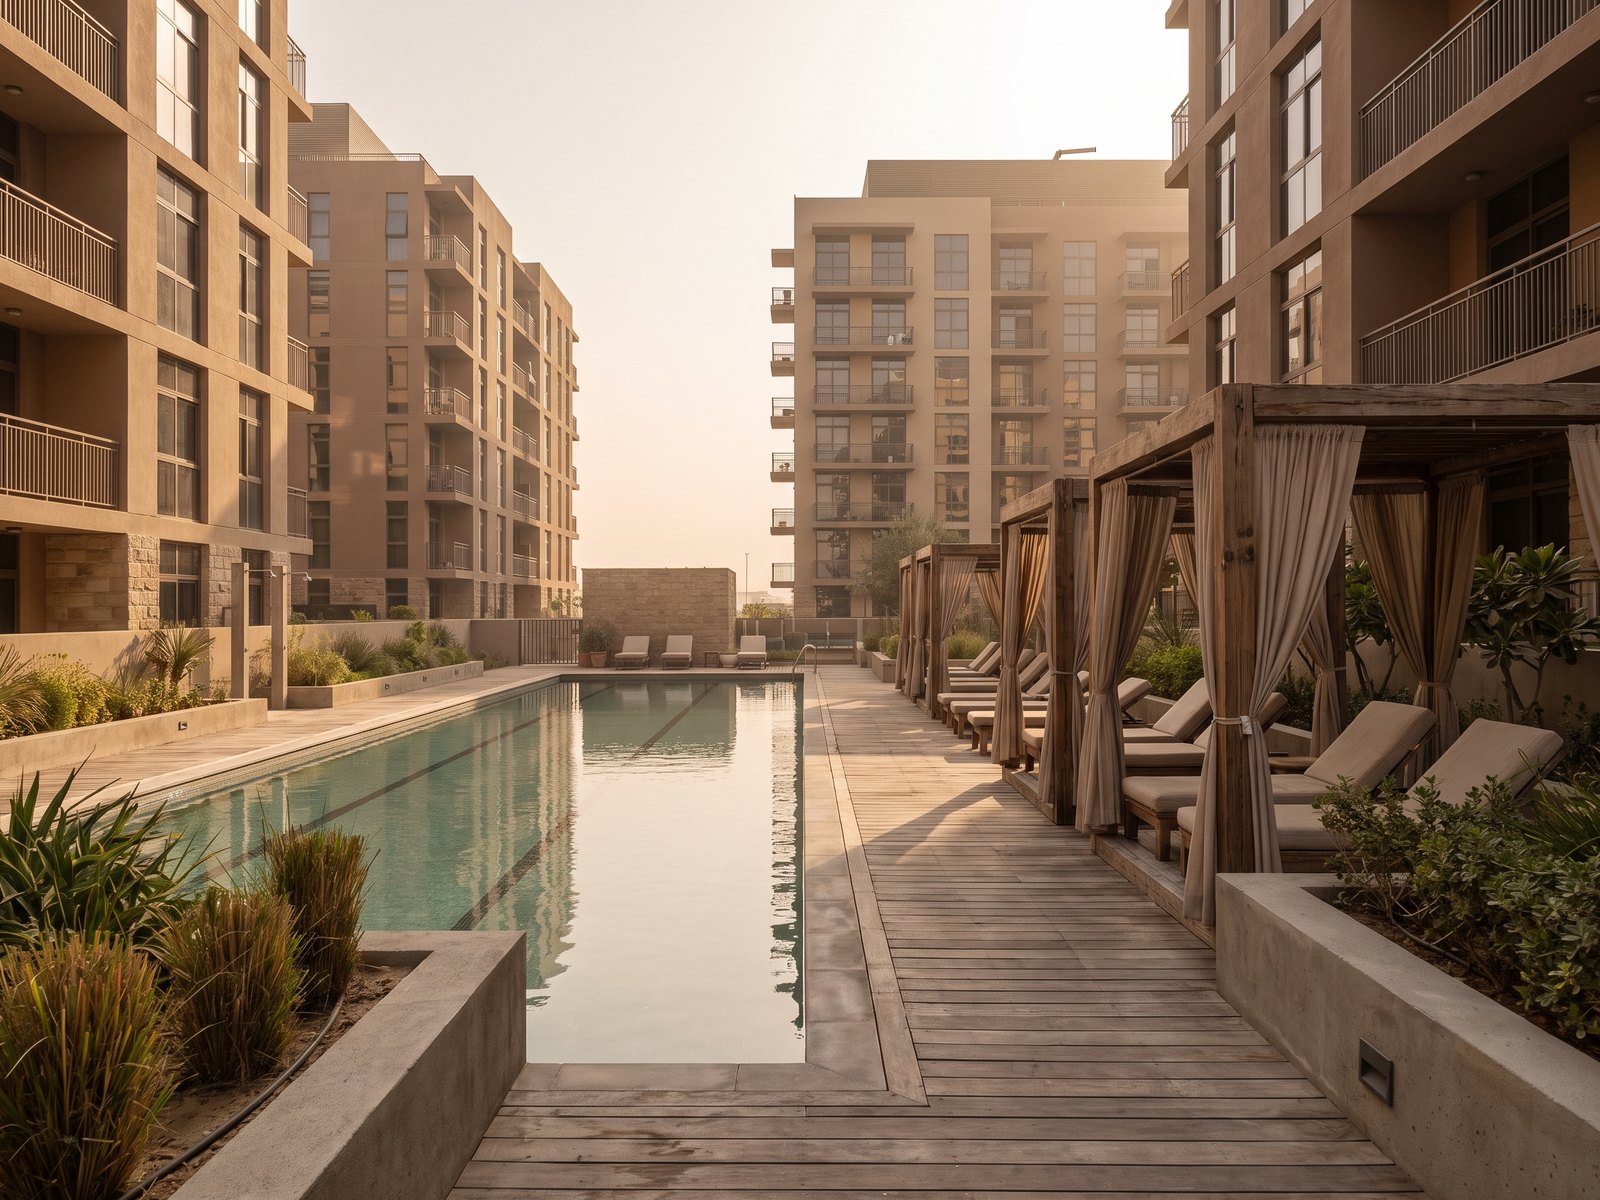
A lagoon-facing one-bed in the first Hartland II crescent.
An 80/20 plan
Bought on an 80/20 payment plan, with handover scheduled for Q2 2027.
What could undo the case: Supply.
A small unit in a district with a lot of similar stock arriving between 2027 and 2029; the exit depends on the lagoon frontage holding its premium.
The facts
Each figure with its basis and its date.
- Asking price
- USD 327 K(AED 1.20 M)
- Asking price as at 12 Sep 2026
- Modelled net yield
- 5.0%
- Base case, after the service charge, a management fee and a void allowance
- Area
- 496 sq ft
- From the listing
- Stage
- Off-plan
- As at 12 Sept 2026
- Service charge
- Not on record yet
- Taken from the building's published budget when we have it
- Handover
- Q2 2027
- Developer schedule
- Community
- MBR City
- As listed
- Unit
- 1 bed
- From the listing
- Profile
- Growth
- What the money does here, in a word
- Reference
- JH-2614
- Reviewed 12 Sept 2026

How the income works
From the rent to what is left, before anything is called net.
- Market rentComparable lettings in the building or communityModelled
- Void allowanceOur assumption for the months between tenantsModelled
- Service chargeDeducted once the building publishes a budgetNot on record yet
- Management feeOur assumption for letting and managementModelled
- Net income5.0% of the asking priceAbout USD 16,338(AED 60,000) a year
5.0%Net yield, modelled, base case
The rent, the void and the fee are our own assumptions. Their figures are published with the full evaluation.
See full assumptions
The modelled net yield starts from the rent that comparable lettings in the same building or community are achieving and takes out the service charge, a management fee and a void allowance before anything is called net. The rent, the fee and the void are our own assumptions, dated 12 September 2026. The price is the asking price on the date shown, not a valuation.
No other cost, growth rate or exit figure is modelled for this property yet. Purchase costs, financing and tax depend on the buyer and are worked through in the full evaluation.
The market around it
- Sep 2026One resale at AED 1.2M against an original AED 1.25M.
- Q2 2027Handover, on the developer’s schedule.
- 2027 to 2029Similar stock arriving across the district.
This is why the case depends on the lagoon frontage holding its premium.

How strong the evidence is
Confidence describes the evidence, not the investment.
What the word means: limitedFew sources, or sources that are not recent, or a gap the evidence cannot close yet. The figure is still shown, with its date, and what is missing is written down beside it.
Limited confidence. Developer pricing from AED 1.14M and one resale at AED 1.2M against an original price of AED 1.25M, September 2026.
As at 12 Sept 2026
What would strengthen this view?
More resales in the crescent, and the rents it achieves once handed over.
What we are watching
Supply
Primary concern
Similar stock arrives in the district between 2027 and 2029, and this is a small unit.
The evidence
Thin
Developer pricing and one resale are the evidence so far.
This is a screening view.
A full Jubilee Heights evaluation adds:
- Scenario testing, with rent, void and exit moved together
- A deeper review of the evidence, with its recency and its limits
- Named risks, each with its effect and our response
- A confidence assessment for every figure
- A management review, signed, with its conditions
Interested in this opportunity?
Discuss 330 Riverside Crescent with us.
- Impression 1 of 3
Peninsula Four, The Plaza
ReadyBusiness Bay · 1 bed · 831 sq ft
USD 545 K (AED 2.00 M)Asking, as at 12 Sep 2026
- Net yield, modelled
- 4.5% base case
- Profile
- Balanced
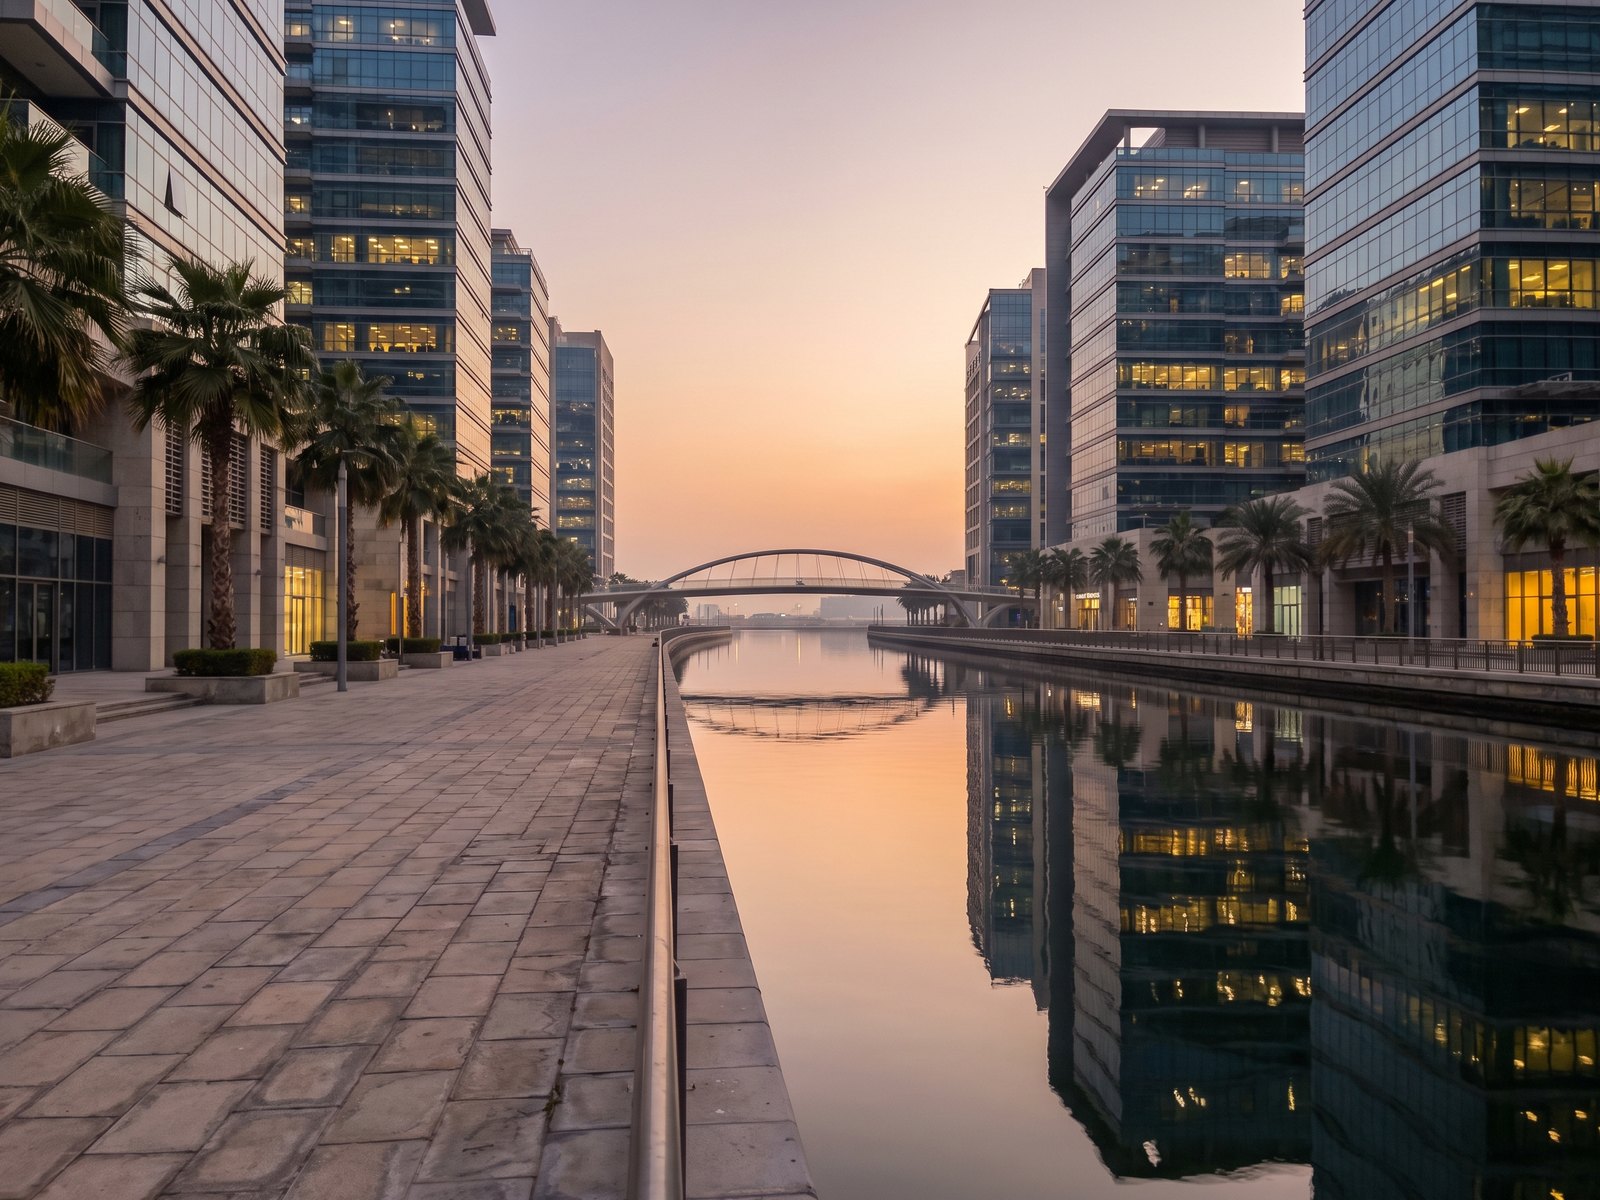
Our viewA Select Group tower on the canal, newly handed over: ready one-beds are asking AED 2.0 to 2.45M, and the canal-side stock lets quickly.
- Impression 1 of 3
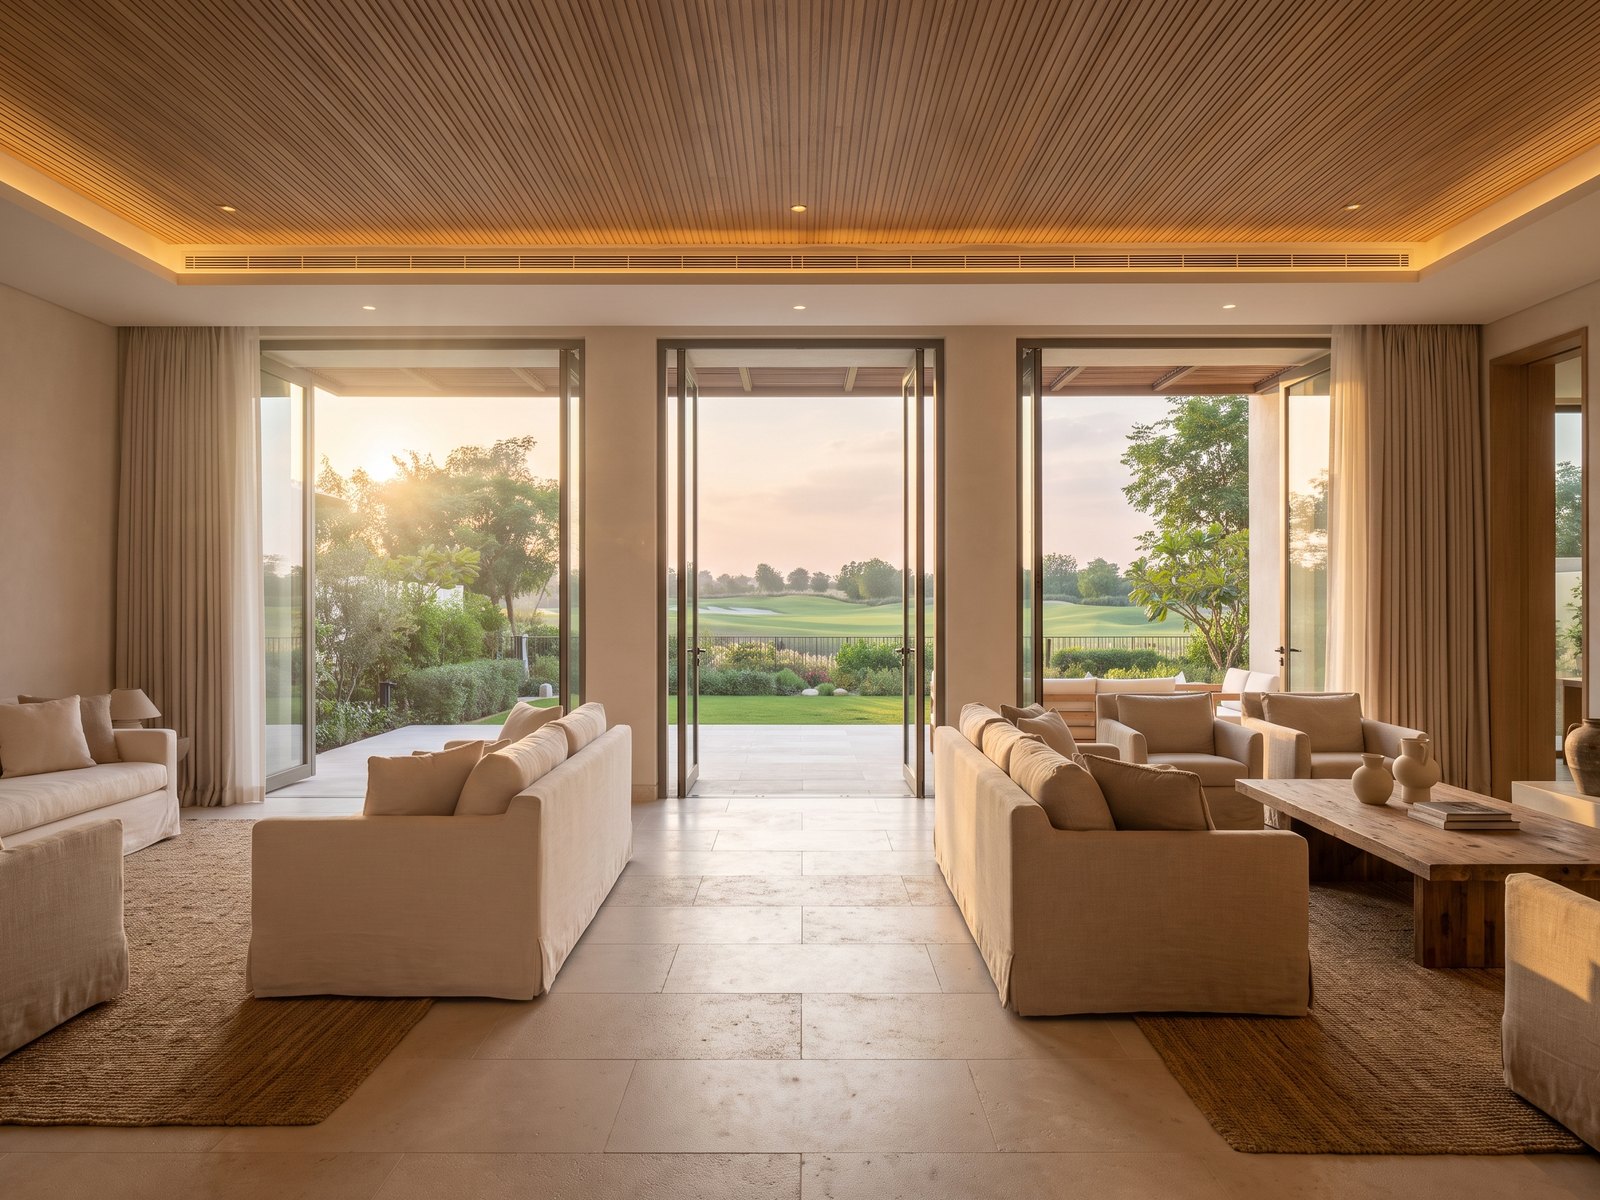
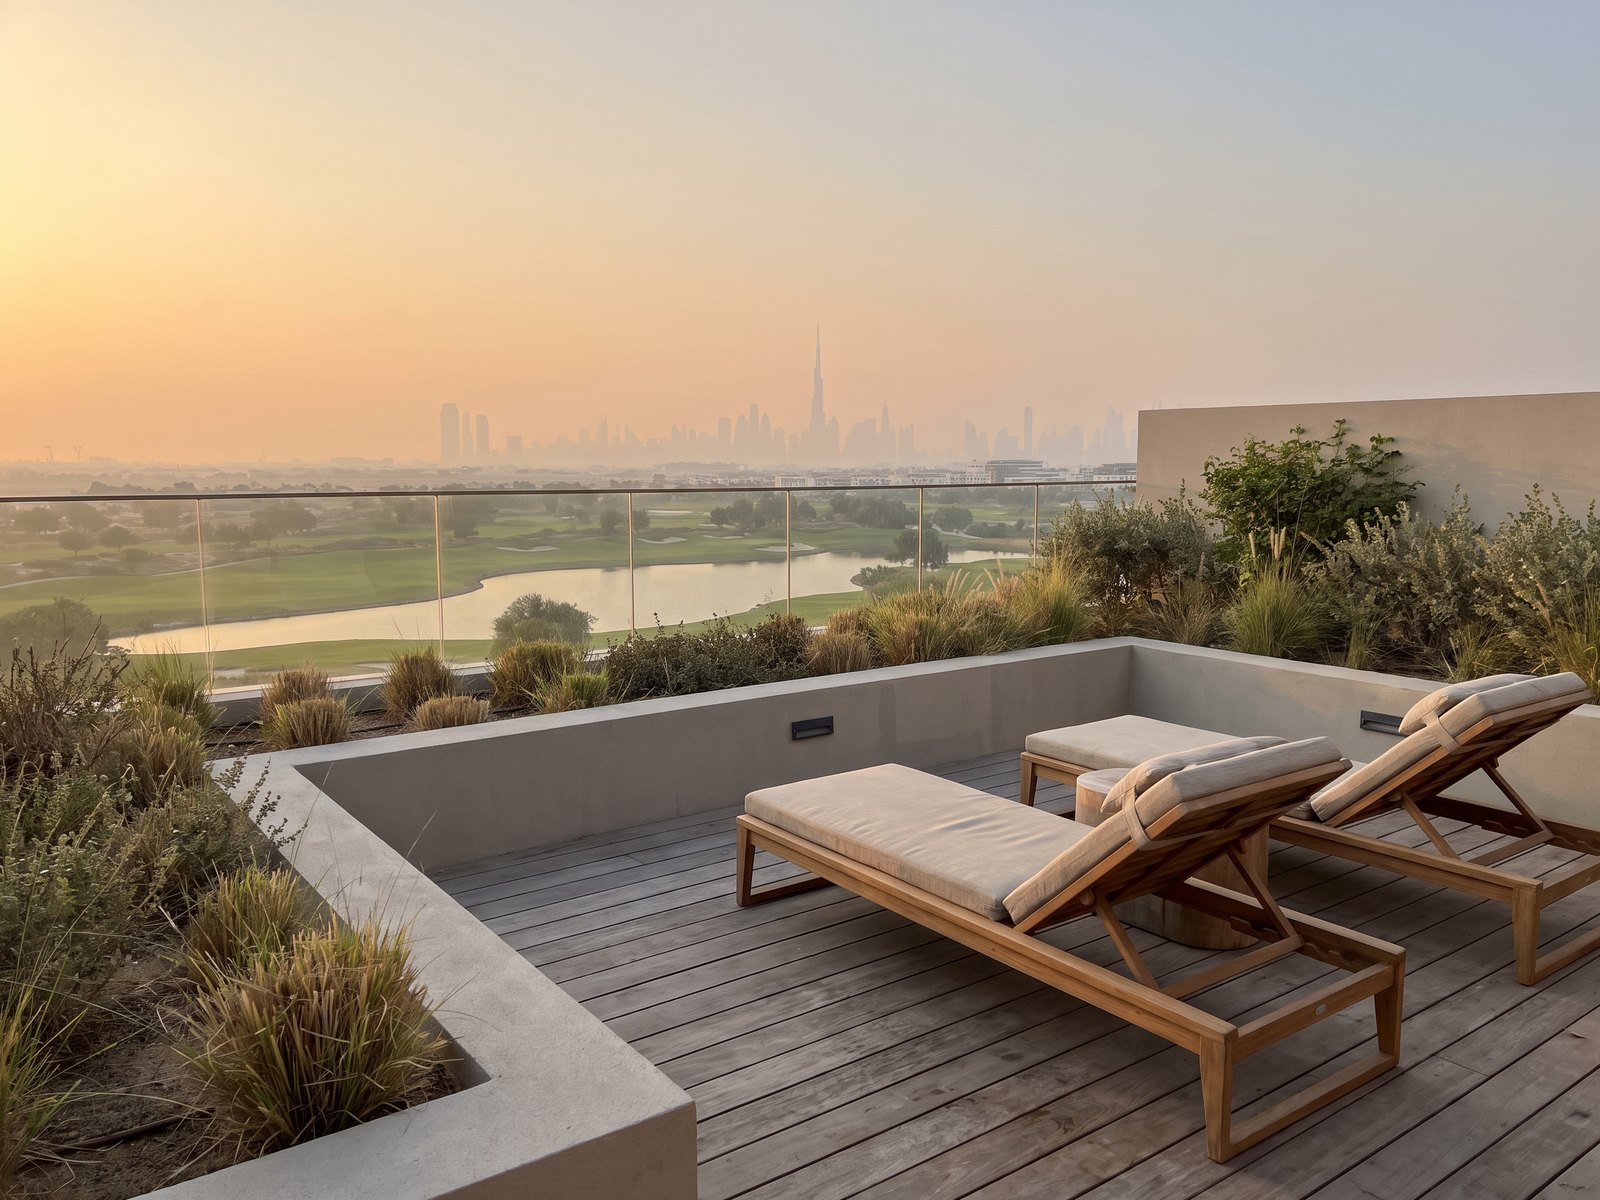
Golf Grove, Dubai Hills Estate
ReadyDubai Hills Estate · 4 bed villa · 3,368 sq ft
USD 2.11 M (AED 7.75 M)Asking, as at 12 Sep 2026
- Net yield, modelled
- 3.4% base case
- Profile
- Growth
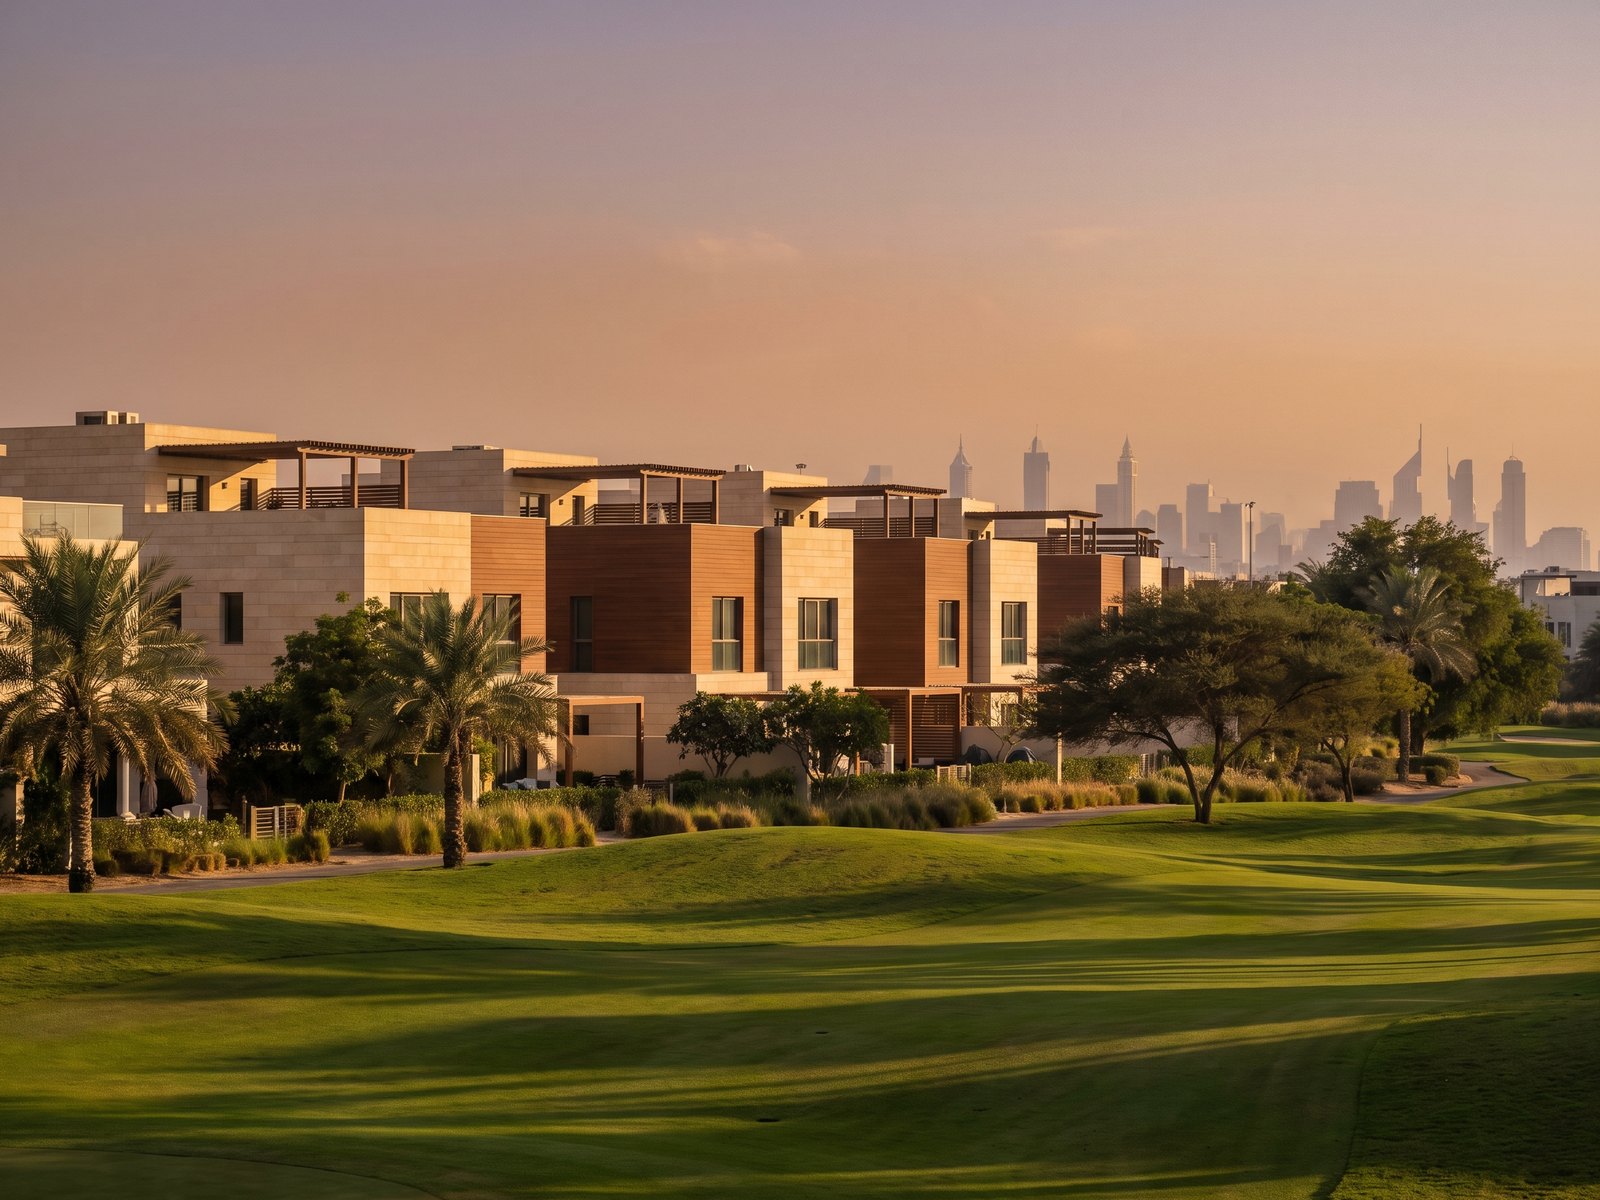
Our viewAn Emaar villa community on the golf course; secondary villas in Dubai Hills trade at about AED 2,700 a square foot and the golf-facing rows have led the estate on price.
- Impression 1 of 3
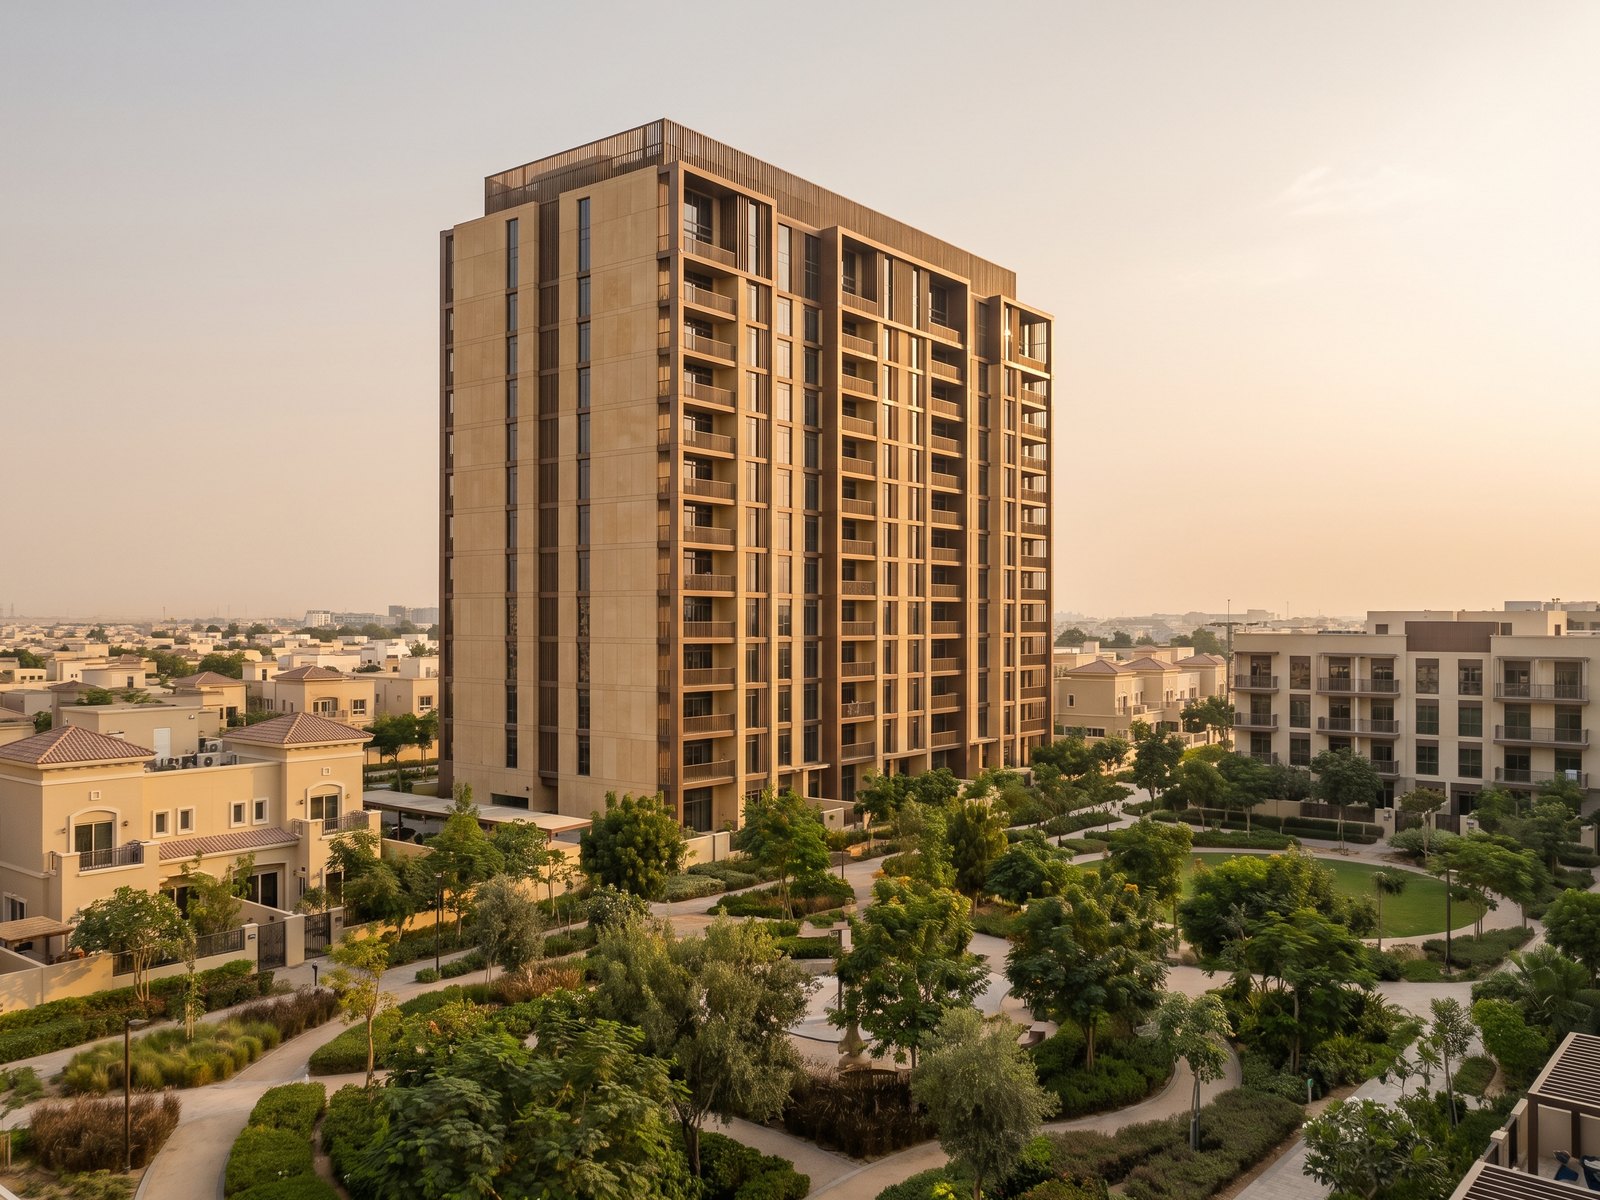
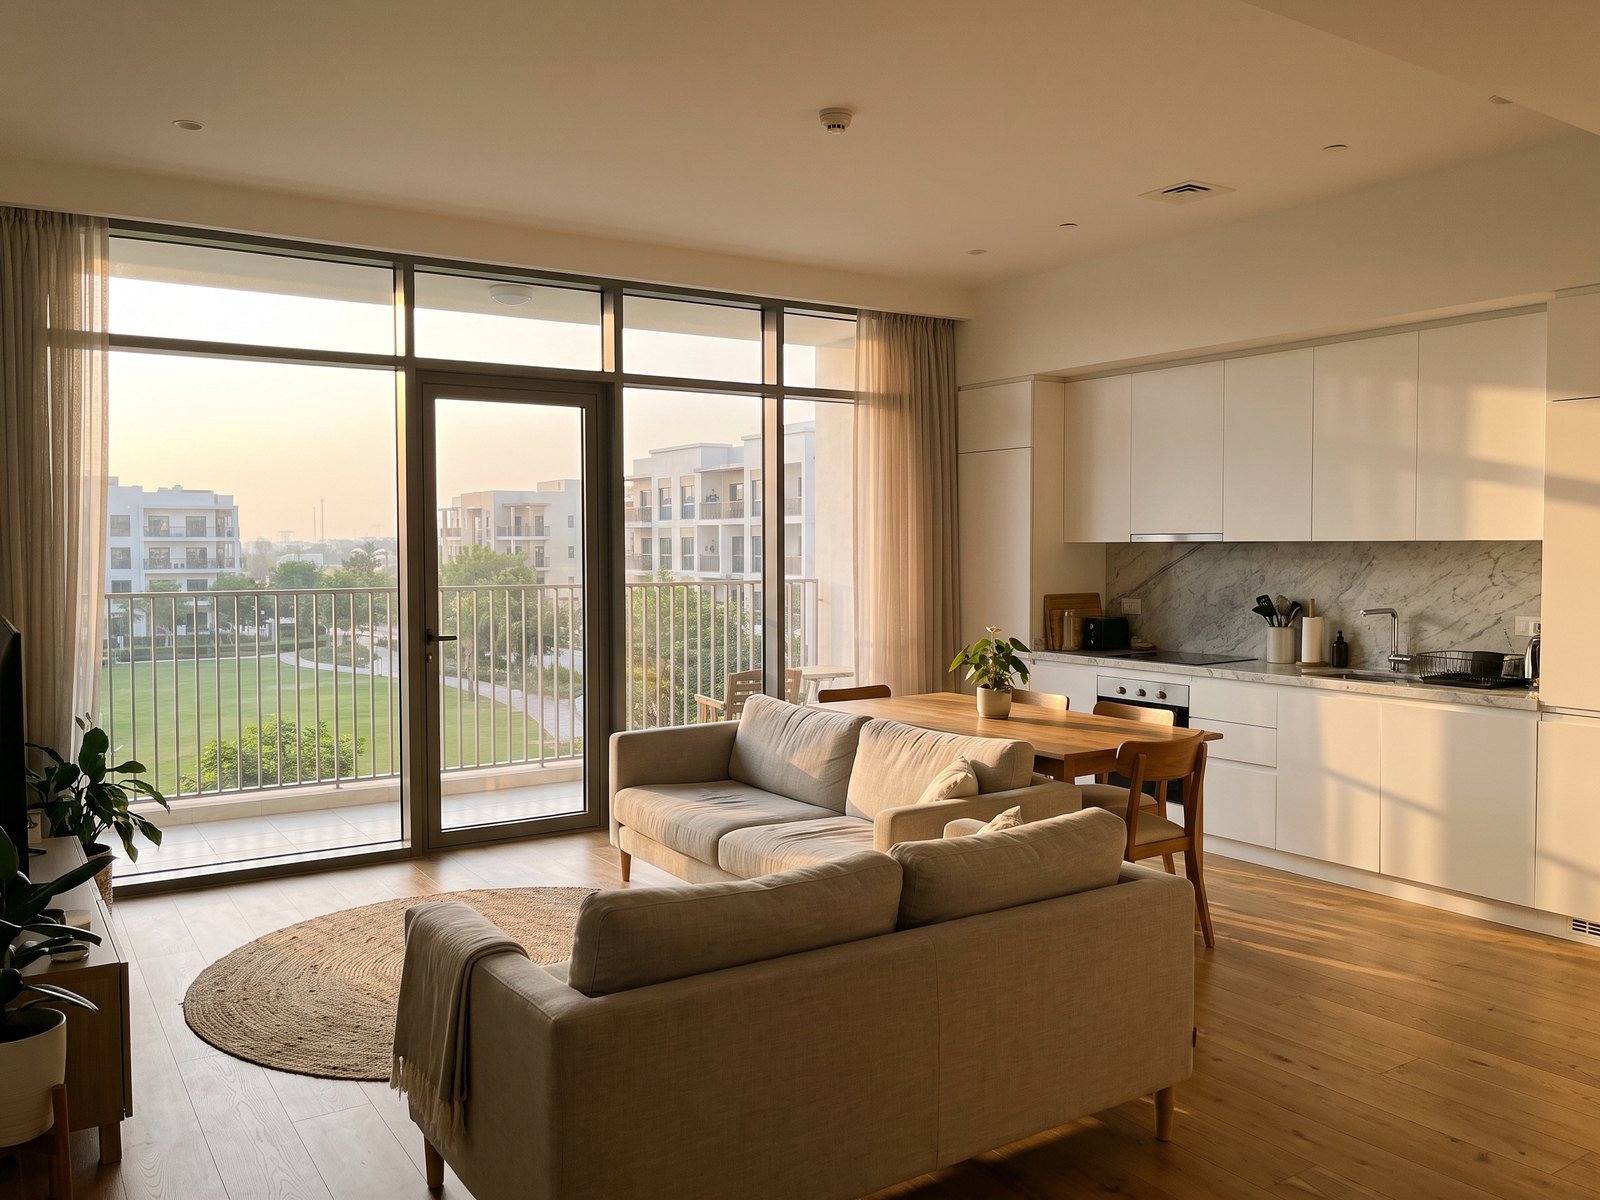
Belgravia Heights I, JVC
ReadyJumeirah Village Circle · 1 bed · 764 sq ft
USD 313 K (AED 1.15 M)Asking, as at 12 Sep 2026
- Net yield, modelled
- 5.9% base case
- Profile
- Income
Our viewAn Ellington building handed over in 2022, so the letting history is real: JVC one-beds are the strongest yielding stock in the city and this one is tenanted.


