
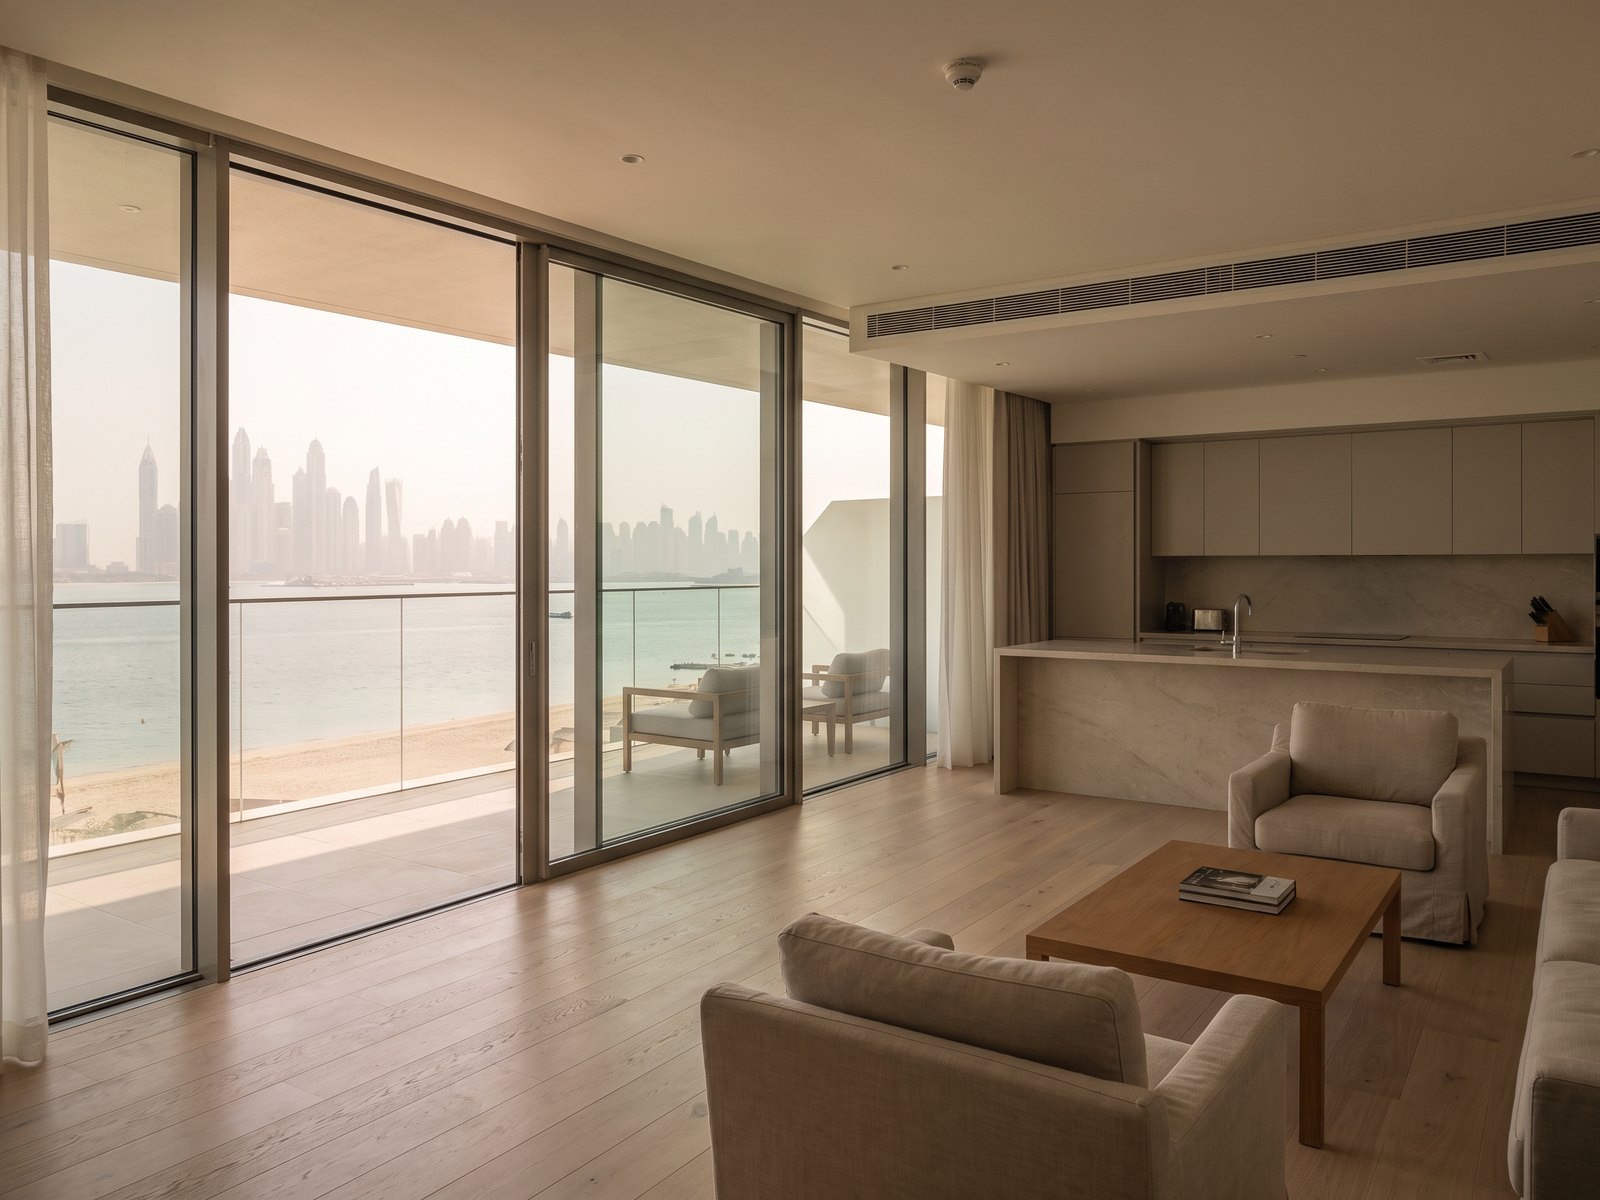
A freehold second home opposite the Burj Al Arab, where the case is the address, not the income.
- Asking price
- USD 1.25 MAED 4.60 M
- Modelled net yield
- 4.1%
- Data confidence
- High
- Best aligned with
- A Dubai second home
- Long-term wealth
- Less convincing for
- Rental incomeA second-home price with a rental yield to match.
Why this is on our list
Freehold, newly
Freehold in a district that was closed to it for years.
The address
Meraas, opposite the Burj Al Arab.
Priced within the range
Two-beds ask AED 4.4 to 5.2M, and this one asks AED 4.6M.
What could undo the case: Scarcity.
A second-home price with a rental yield to match: the case rests on the address holding its scarcity, not on the income.
The facts
Each figure with its basis and its date.
- Asking price
- USD 1.25 M(AED 4.60 M)
- Asking price as at 12 Sep 2026
- Modelled net yield
- 4.1%
- Base case, after the service charge, a management fee and a void allowance
- Area
- 1,292 sq ft
- From the listing
- Stage
- Ready
- As at 12 Sept 2026
- Service charge
- 5.99 USD / sq ft (AED 22.00)
- 2026 budget
- Community
- Umm Suqeim
- As listed
- Unit
- 2 bed
- From the listing
- Profile
- Balanced
- What the money does here, in a word
- Reference
- JH-2624
- Reviewed 12 Sept 2026

How the income works
From the rent to what is left, before anything is called net.
- Market rentComparable lettings in the building or communityModelled
- Void allowanceOur assumption for the months between tenantsModelled
- Service chargeAED 22 a sq ft × 1,292 sq ft, 2026 budget−USD 7,740(AED 28,424) a year
- Management feeOur assumption for letting and managementModelled
- Net income4.1% of the asking priceAbout USD 51,355(AED 188,600) a year
4.1%Net yield, modelled, base case
The rent, the void and the fee are our own assumptions. Their figures are published with the full evaluation.
See full assumptions
The modelled net yield starts from the rent that comparable lettings in the same building or community are achieving and takes out the service charge, a management fee and a void allowance before anything is called net. The rent, the fee and the void are our own assumptions, dated 12 September 2026. The price is the asking price on the date shown, not a valuation.
No other cost, growth rate or exit figure is modelled for this property yet. Purchase costs, financing and tax depend on the buyer and are worked through in the full evaluation.

How strong the evidence is
Confidence describes the evidence, not the investment.
What the word means: highSeveral sources, recent, with the gaps closed: the further lettings or the budget a moderate figure was waiting for.
High confidence. Resale listings and DLD transactions in Asayel, and its letting pages, September 2026.
As at 12 Sept 2026
What we are watching
Scarcity
Primary concern
The case rests on the address holding its scarcity.
The income
Secondary
Two-beds let at AED 220 to 260K, a yield to match a second-home price.
This is a screening view.
A full Jubilee Heights evaluation adds:
- Scenario testing, with rent, void and exit moved together
- A deeper review of the evidence, with its recency and its limits
- Named risks, each with its effect and our response
- A confidence assessment for every figure
- A management review, signed, with its conditions
Interested in this opportunity?
Discuss Asayel 3 with us.
- Impression 1 of 3
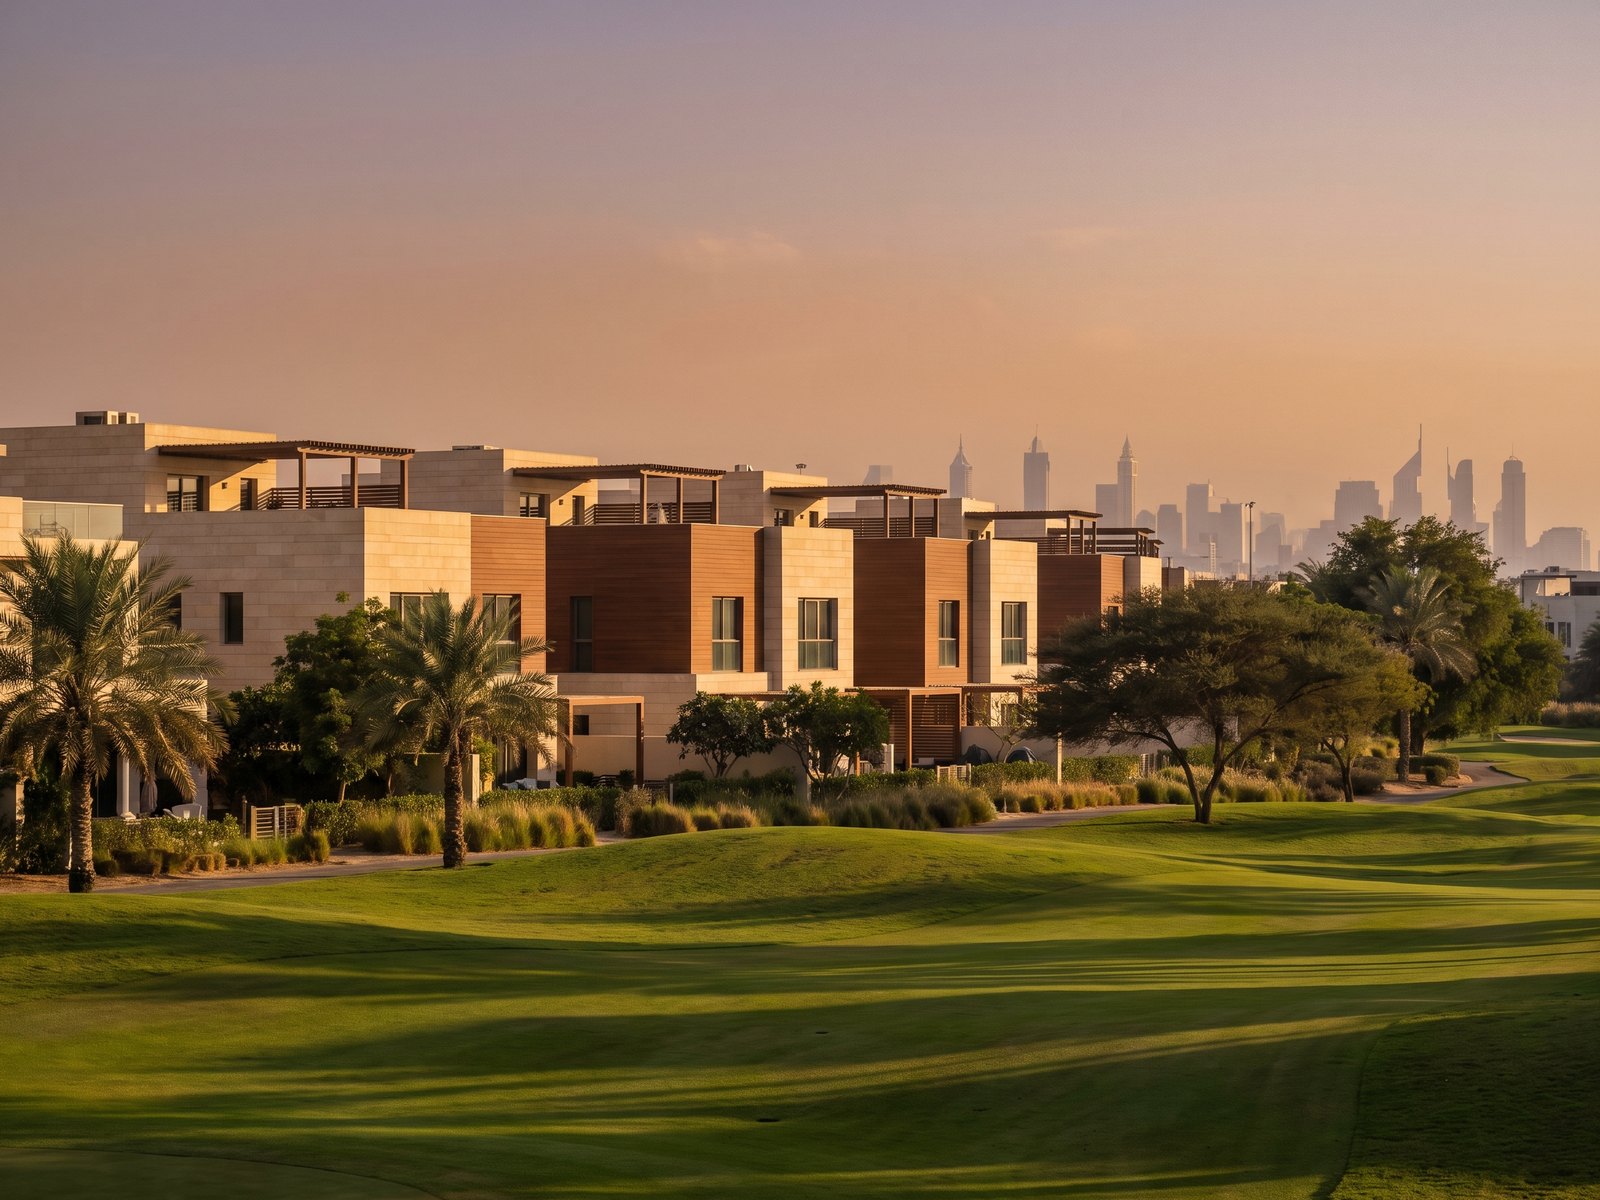
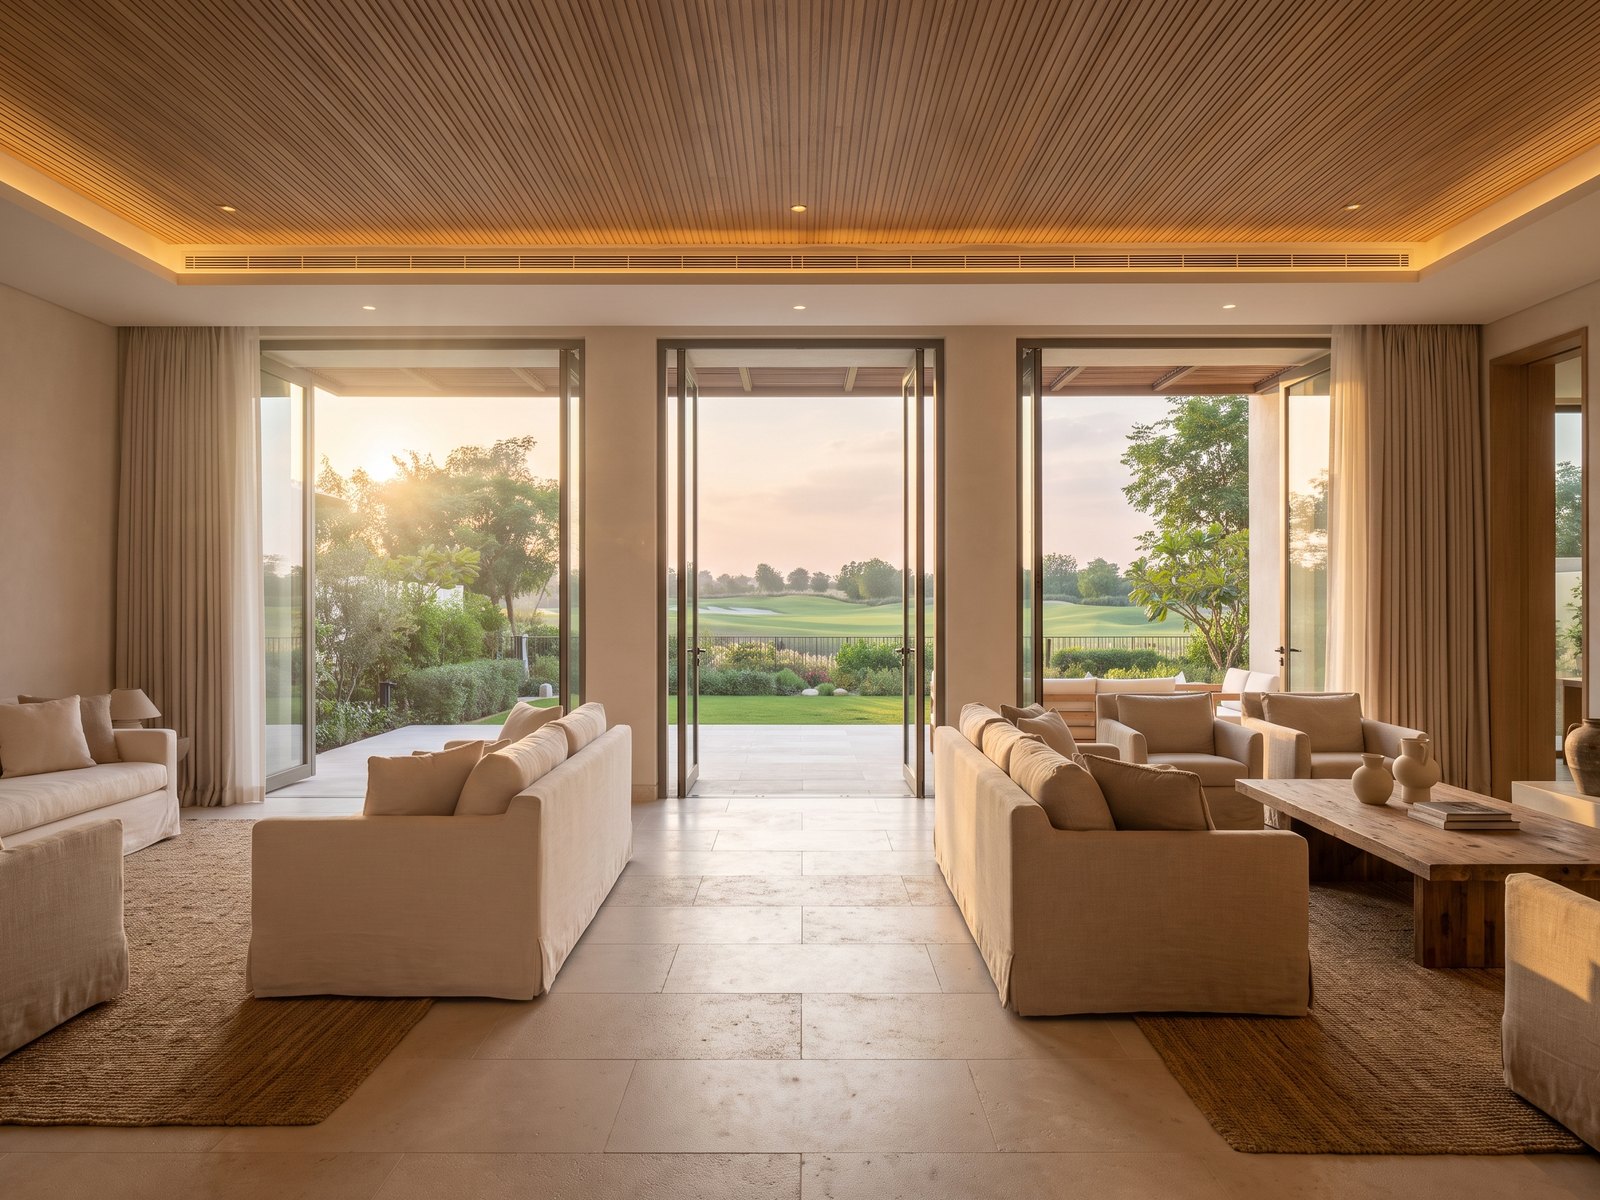
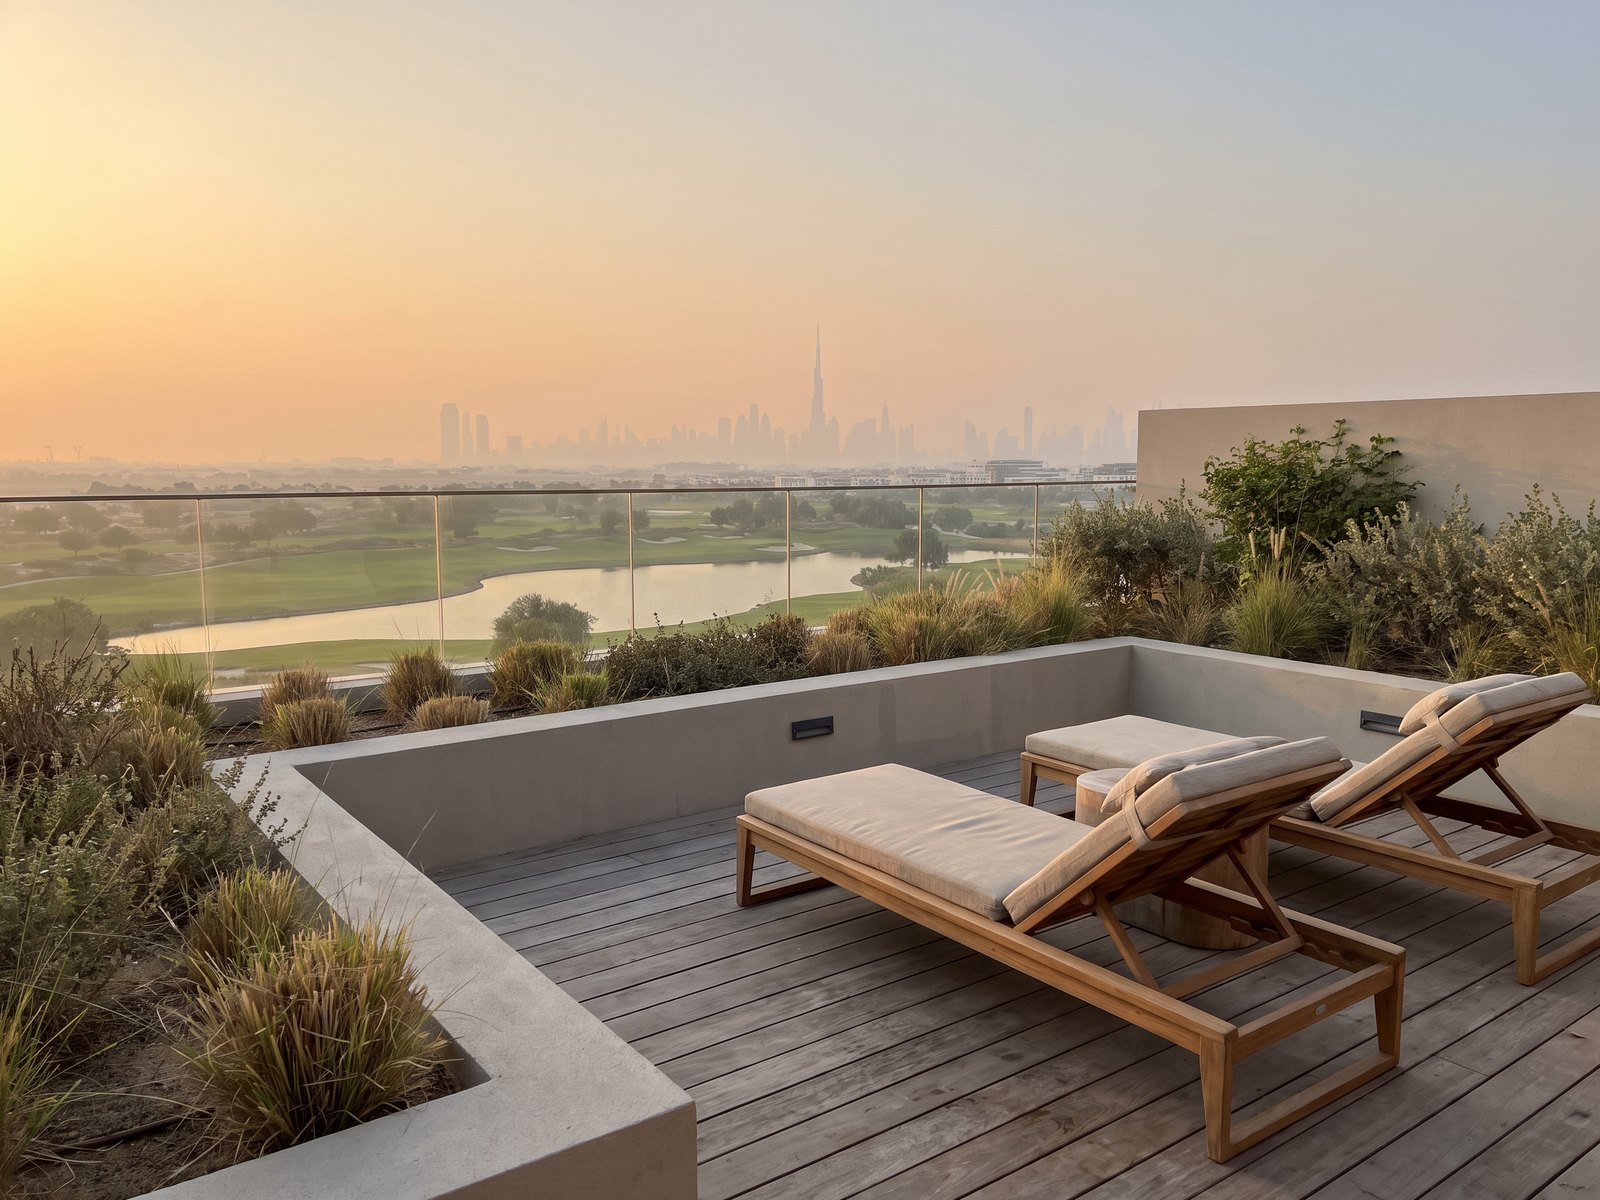
Golf Grove, Dubai Hills Estate
ReadyDubai Hills Estate · 4 bed villa · 3,368 sq ft
USD 2.11 M (AED 7.75 M)Asking, as at 12 Sep 2026
- Net yield, modelled
- 3.4% base case
- Profile
- Growth
Our viewAn Emaar villa community on the golf course; secondary villas in Dubai Hills trade at about AED 2,700 a square foot and the golf-facing rows have led the estate on price.
- Impression 1 of 3
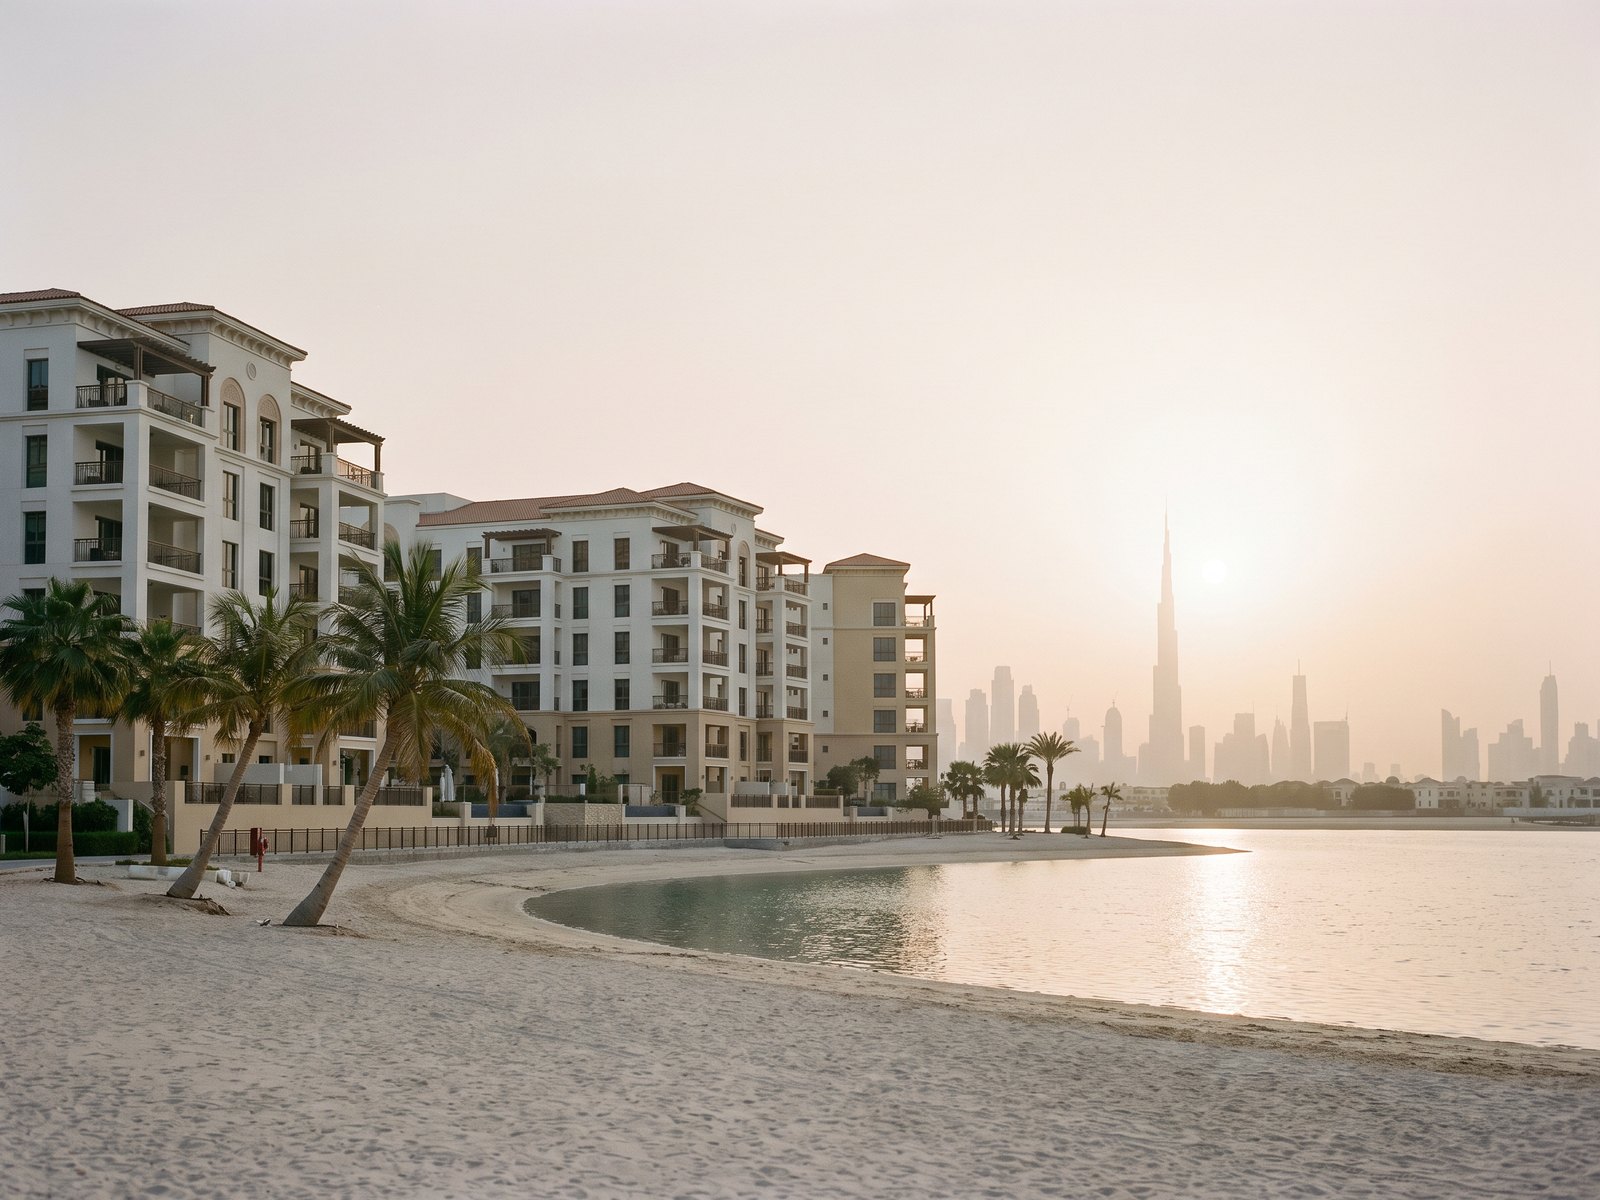
Bayshore, Creek Beach
ReadyDubai Creek Harbour · 2 bed · 1,105 sq ft
USD 667 K (AED 2.45 M)Asking, as at 12 Sep 2026
- Net yield, modelled
- 4.8% base case
- Profile
- Balanced
Our viewAn Emaar beachfront building that is finished and lived in: two-beds ask about AED 2.45M against a DLD average near AED 2.32M, and let at AED 140 to 160K.


